

California home insurance is a non-negotiable investment for every property owner in the Golden State. With its diverse geography, ranging from coastal cities to mountain communities and sprawling urban centers, the state presents a unique set of risks that directly influence homeowners insurance rates, coverage options, and policy structure. Whether you own a single-family residence in San Diego, a condo in San Francisco, or a historic property in Sacramento, understanding how California homeowners insurance works can save you thousands of dollars and prevent devastating financial losses during a disaster. This comprehensive guide breaks down everything you need to know about residential property coverage in California, from policy types and premium factors to practical strategies for reducing costs and maximizing protection.
What Is California Home Insurance and Why It Matters

California home insurance, also known as homeowners insurance or residential property coverage, is a bundled policy designed to protect your dwelling, personal belongings, and financial liability against covered perils. Standard policies typically include dwelling coverage, personal property protection, liability insurance, and additional living expenses. Because California faces elevated risks from wildfires, earthquakes, and coastal flooding, the insurance landscape here differs significantly from most other states. Insurers carefully evaluate location-specific hazards when underwriting policies, which means your premium and coverage terms can vary dramatically depending on where your property sits.
Understanding the fundamentals of California dwelling fire policies is the first step toward making informed decisions. A standard HO-3 policy covers most perils on your home structure, while personal property is protected on a named-perils basis. For high-value properties or those in extreme-risk zones, specialty endorsements and separate policies may be necessary to fill gaps in standard coverage.
Key Coverage Types in California Home Insurance Policies
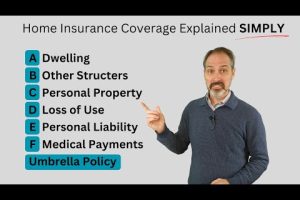
Dwelling Coverage (Coverage A)

Dwelling coverage pays for the repair or reconstruction of your home’s physical structure after a covered event such as a fire, windstorm, or hail damage. In California, insurers calculate dwelling limits based on local construction costs, square footage, and building materials. A critical consideration is ensuring your coverage limit reflects current replacement cost values rather than market value, as construction expenses in California can be substantially higher than the national average.
Personal Property Coverage (Coverage C)
This component reimburses you for damaged or stolen personal belongings, including furniture, electronics, clothing, and appliances. Standard policies typically cover personal property at 50 to 70 percent of your dwelling coverage limit. For high-value items such as jewelry, artwork, or collectibles, scheduling additional endorsements or floaters is strongly recommended, especially given the theft and vandalism risks in certain California metropolitan areas.
Liability Protection (Coverage E)
Liability coverage protects you financially if someone is injured on your property and decides to sue. Standard limits typically start at $100,000, but experts in the California insurance market recommend at least $300,000 to $500,000, given the state’s litigious environment and high cost of medical care and legal settlements.
Additional Living Expenses (Coverage D)
If your home becomes uninhabitable due to a covered loss, additional living expenses coverage pays for temporary housing, meals, and other necessary costs while repairs are underway. This is particularly important in California, where displaced homeowners may face significantly higher temporary housing costs in competitive real estate markets like Los Angeles or the Bay Area.
Why California Home Insurance Costs More Than the National Average
The average annual California homeowners insurance premium sits notably above the national average, driven by several compounding risk factors. Understanding these variables helps homeowners set realistic expectations and explore strategies for managing costs effectively.
Wildfire Risk and Its Impact on Premiums
California leads the nation in wildfire frequency and severity. Insurance carriers use sophisticated catastrophe modeling tools to assess wildfire exposure at the ZIP code and parcel level. Properties located in the Wildland-Urban Interface (WUI), areas where developed communities meet undeveloped wilderness, face the highest premiums and, in some cases, difficulty securing coverage altogether. Insurers also consider your home’s defensible space, roof material, and proximity to fire stations when calculating rates.
Earthquake Exclusion and Earthquake Insurance Riders
Standard California home insurance policies explicitly exclude earthquake damage. Given that California sits on multiple major fault lines, this exclusion is significant. Earthquake insurance is typically offered as a separate policy or an endorsement, and premiums vary widely based on seismic zone classification, soil type, and building construction. While earthquake coverage involves its own deductible—often expressed as a percentage of dwelling coverage rather than a fixed dollar amount—it remains essential for comprehensive risk management.
Theft, Vandalism, and Coastal Exposure Factors
Urban areas in California, particularly Los Angeles, Oakland, and San Jose, experience elevated rates of property crime, which influences both premiums and underwriting scrutiny. Additionally, coastal properties face unique risks from wind, storm surge, and salt air corrosion, all of which can increase insurance costs and limit available carriers.
Comparing Popular Home Insurance Providers in California
Not all insurance carriers operate equally in California. Due to the state’s elevated risk profile, some major insurers have pulled back or restricted offerings in high-fire zones. The table below compares key providers based on general market positioning, average annual premium ranges, and notable policy features relevant to California homeowners.
| Provider | Avg. Annual Premium Range | Key Strengths | Notable Consideration |
| California FAIR Plan | Varies (higher for high-risk zones) | Last-resort coverage for denied applicants | Limited coverage scope; intended as a safety net |
| State Farm | $1,400–$2,200 | Strong customer service, broad agent network | May limit new policies in severe wildfire zones |
| Allstate | $1,500–$2,500 | Robust endorsement options, claims flexibility | Premiums can be elevated in WUI areas |
| Lemonade | $1,100–$1,900 | Digital-first experience, fast claims processing | May not be available in all high-risk zones |
| USAA | $1,200–$2,000 | Competitive rates, military benefits | Exclusively available to military members and families |
When comparing California dwelling fire insurance options, always evaluate the carrier’s financial stability, claims processing reputation, and willingness to write policies in your specific geographic area. An online California home insurance quote can give you a baseline, but speaking directly with an independent agent who understands local market dynamics often yields better results.
How to Lower Your California Home Insurance Premium
Reducing your homeowners insurance costs in California is achievable through a combination of proactive risk mitigation and smart shopping strategies. Here are expert-recommended approaches:
- Install fire-resistant roofing and siding. Class A fire-rated materials can qualify you for significant premium discounts, particularly in wildfire-prone regions.
- Invest in a monitored fire and burglar alarm system. Insurers reward homes with verified alarm systems that directly notify emergency services.
- Increase your deductible. Raising your deductible from $500 to $1,000 or $2,500 can lower your annual premium noticeably, though you must be comfortable covering the higher out-of-pocket cost in a claim.
- Bundle your home and auto insurance. Multi-policy discounts through a single carrier can reduce your total insurance spend by 10 to 25 percent.
- Maintain strong credit-based insurance scores. In California, insurers may use credit-based insurance scores as a rating factor, so maintaining good credit health directly impacts your premiums.
- Review and update your policy annually. As construction costs and local risk assessments shift, your coverage needs and premium opportunities change. Regular reviews prevent overpaying or being underinsured.
Frequently Asked Questions About California Home Insurance
Is earthquake insurance required for California homeowners?
No, earthquake insurance is not legally required in California, and standard homeowners policies exclude earthquake damage. However, given the state’s seismic activity, purchasing a separate earthquake policy or endorsement is strongly recommended for most homeowners, especially those living near known fault lines or in areas with soft soil conditions that amplify shaking.
Can I get homeowners insurance if I live in a high-risk wildfire zone?
While some carriers have restricted or declined new policies in the most severe wildfire risk areas, options still exist. The California FAIR Plan provides basic property insurance as a last resort for homeowners who cannot obtain coverage through the voluntary market. Many private insurers also continue to write policies in wildfire zones, though premiums are higher and may include specific mitigation requirements such as vegetation clearance and ember-resistant vents.
What is the average cost of home insurance in California compared to other states?
California’s average annual homeowners insurance premium generally runs higher than the national average, often between $1,400 and $2,500 depending on location, construction type, and risk exposure. Coastal and high-fire-risk areas can push premiums significantly above these ranges, while inland suburban properties may fall closer to or slightly above the national median.
Does flood insurance come standard with a California home insurance policy?
No, standard homeowners insurance does not cover flood damage, including flooding from storms, mudflows, or levee failure. California homeowners in flood-prone areas should consider purchasing a separate flood insurance policy through the National Flood Insurance Program (NFIP) or a private flood insurer. Given California’s variable weather patterns and the increasing frequency of atmospheric river events, flood coverage is becoming an increasingly relevant consideration.
How long does it take to receive a California home insurance quote online?
Most online platforms and carrier websites can generate a California home insurance quote within minutes, provided you have basic information about your property, including the address, square footage, construction year, and coverage preferences. For a more tailored and potentially more competitive quote, consulting an independent insurance broker who represents multiple carriers is often the fastest path to finding the best coverage at the best price.
Conclusion

Navigating the California home insurance landscape requires awareness, preparation, and a proactive mindset. The state’s unique combination of wildfire exposure, seismic activity, coastal risks, and elevated construction costs creates an insurance environment that demands thoughtful coverage decisions. By understanding the key coverage components, comparing providers, implementing risk-reducing upgrades, and staying informed about policy options, California homeowners can secure robust protection at manageable costs. Whether you are purchasing your first home in the state or reassessing an existing policy, investing time in understanding your residential property coverage is one of the most financially prudent decisions you can make. Start by requesting a detailed California home insurance quote today, review your policy limits annually, and never hesitate to seek expert guidance from a licensed insurance professional who specializes in the California market.