

For millions of residents across the Golden State, securing the right California homeowners insurance is not just a financial decision—it is an absolute necessity. Living in a state renowned for its stunning coastline, vibrant cities, and diverse landscapes comes with unique risks that standard insurance policies simply cannot ignore. From the devastating wildfires that sweep through parched hillsides to the seismic activity that shifts the very foundation of your property, protecting your home requires a deep understanding of local coverage nuances. Whether you are a first-time homebuyer navigating the labyrinth of property protection or a seasoned resident looking to optimize your existing policy, knowing the intricacies of your coverage can mean the difference between a seamless recovery and a financial catastrophe. This comprehensive guide dives deep into the specifics of California property insurance, breaking down coverage types, pricing factors, and the often-overlooked programs designed to keep your investment safe.
Why California Homeowners Insurance is Unique
Unlike many other states, the insurance landscape in California is shaped heavily by environmental factors and stringent regulatory frameworks. The state’s Mediterranean climate, while beautiful, creates a perfect storm for natural disasters. Insurers must account for the high probability of catastrophic events, which drives premiums and coverage requirements up significantly. When you shop for California home insurance quotes, you will notice that providers evaluate risk differently than they do in other regions. The state’s Insurance Code and the Department of Insurance closely regulate how carriers operate, ensuring consumer protections but also limiting the flexibility insurers have when setting rates. Furthermore, the increasing frequency of extreme weather events, driven by climate change, has forced the industry to re-evaluate underwriting guidelines constantly. Understanding this backdrop is the first step toward making informed decisions about your dwelling coverage California policies.

Breakdown of California Homeowners Insurance Coverage
Navigating the different components of a home insurance policy can feel overwhelming, especially when you are dealing with complex state-specific endorsements. The standard HO-3 policy provides a framework, but California residents often need to layer on additional protections. Let us break down the essential segments of your coverage so you can confidently discuss your needs with agents or compare competing offers.
The Wildfire and Natural Disaster Factor
At the core of any robust policy lies the understanding of what perils are actually covered. Standard California homeowners insurance typically protects against fire, lightning, and smoke damage. However, in a state where wildfires are an annual threat, the scope of coverage requires careful scrutiny. Most standard policies include dwelling coverage California provisions that address fire damage, but they might exclude specific earthquake-related fire losses unless explicitly added. Furthermore, windstorms and debris flows—common companions to severe wildfires—are often covered under the standard homeowners form, but the limits may vary drastically from one insurer to another. It is crucial to verify that your policy limits actually reflect the current replacement cost of your home, not just its market value, to ensure you are adequately shielded against total loss scenarios.
Dwelling Coverage and Other Structures
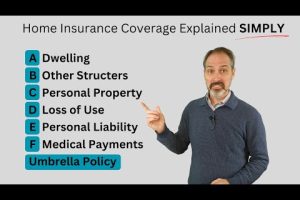
Dwelling coverage is the cornerstone of your policy, paying for the repair or reconstruction of your home’s physical structure if damaged by a covered peril. In California, this must account for the high cost of labor and materials, which are significantly inflated due to strict building codes and the remote locations of many properties. Other structures coverage extends to detached garages, fences, and swimming pools, usually capping at a percentage of your dwelling limit. A common mistake homeowners make is assuming their policy automatically adjusts for inflation; however, without an inflation guard endorsement, your dwelling coverage California limits might fall short of actual rebuilding expenses. Always request a replacement cost estimate from your insurer and cross-reference it with local construction data to ensure your limits are adequate.
Personal Property, Liability, and Loss of Use
Your belongings inside the home—furniture, electronics, clothing, and appliances—fall under personal property coverage. For Californians, this often means safeguarding high-value items like artwork or wine collections, which typically require separate scheduled personal property floaters. Additionally, loss of use coverage, also known as additional living expenses (ALE), kicks in when your home becomes uninhabitable due to a covered event. Given California’s frequent wildfire evacuations, robust ALE coverage is vital, ensuring you can maintain your standard of living in a temporary residence while your property is restored. Equally important is liability protection, which covers medical bills and legal fees if someone is injured on your property. In a litigious state like California, maintaining a solid liability limit is non-negotiable for comprehensive risk management.
Understanding the Cost of California Homeowners Insurance
The cost of California homeowners insurance remains a hot topic for prospective and current homeowners alike. On average, Californians pay significantly more than the national average for property protection, driven by the elevated risk of wildfires, earthquakes, and theft in densely populated urban centers. When evaluating the cost of California homeowners insurance, several critical factors dictate your monthly premium. Your home’s location is paramount; properties in designated Wildland-Urban Interface (WUI) zones face drastically higher rates due to vegetation density and proximity to fire-prone areas. Additionally, the age of your roof, the presence of fire-resistant building materials, and the distance from a local fire station all influence the final quote you receive. Maintaining a strong credit-based insurance score and bundling your auto and home policies are proven strategies to mitigate these elevated costs. Furthermore, the construction class of your home—whether it is frame, masonry, or fire-resistive—plays a massive role in determining how much you will pay for your dwelling coverage California residents deserve.
The FAIR Plan: When Standard Insurance Falls Short
One of the most critical components of the California insurance landscape is the FAIR Plan, which stands for Financial Access to Property Insurance Requirements. As devastating wildfires have become more frequent and severe, many standard carriers have withdrawn from high-risk areas or drastically limited their offerings. This is where the FAIR Plan steps in as an insurer of last resort. The FAIR Plan is not a standalone insurance policy but rather a collaborative safety net provided by participating insurance companies when you cannot secure coverage in the voluntary market. However, it is essential to understand that FAIR Plan policies are basic. They provide bare-bones dwelling coverage California residents need to protect their physical structures, but they typically exclude personal property and liability coverage. Therefore, if you secure a FAIR Plan, purchasing a wrap-around policy or standalone personal articles policy is mandatory to achieve comprehensive protection.

Comparing California Home Insurance Options
To truly grasp the variations in the marketplace, it helps to visually compare how different coverage structures address specific risks. The following table outlines standard options versus high-risk considerations for property owners in the Golden State.
| Coverage Aspect | Standard Market Policy | FAIR Plan / High-Risk Option |
| Dwelling Coverage | Comprehensive repair and replacement | Basic structural repair and replacement |
| Personal Property | Full coverage with sub-limits | Typically excluded entirely |
| Liability Protection | Included up to policy limits | Typically excluded entirely |
| Earthquake Coverage | Usually excluded, requires endorsement | Not included, requires separate policy |
| Wildfire Protection | Included as standard fire peril | Included as standard fire peril |
Practical Recommendations and Expert Tips
Securing the best possible protection for your California home requires proactive effort. Do not wait until the last minute before fire season or an earthquake strikes to realize your policy is insufficient. Start by conducting a thorough home inventory, documenting every valuable item with photographs and receipts. This inventory expedites the claims process should a loss occur. Second, invest in mitigation strategies that insurers actively reward. You should focus on the following actionable steps to reduce your premiums and fortify your home against future disasters:
- Installing Class A fire-rated roofing materials and ember-resistant vents
- Clearing defensible space around your property to reduce wildfire risk
- Upgrading aging plumbing and electrical systems to prevent water and fire damage
- Adding smart home safety devices like leak detectors and fire alarms
Finally, always review your policy annually. The cost of California homeowners insurance fluctuates based on market conditions and reinsurance costs, and an annual review ensures your dwelling coverage California residents need remains aligned with the actual cost of construction in your specific zip code.
Frequently Asked Questions
- How much does California homeowners insurance cost on average? The average cost of California homeowners insurance is roughly $1,800 to $2,500 per year, which is considerably higher than the national average. This variance depends heavily on your location, construction type, and claims history, with high-risk wildfire zones paying significantly more than coastal or inland metropolitan areas.
- Is earthquake coverage included in standard California home insurance? No, standard California homeowners insurance does not include earthquake coverage. Because the state sits on multiple major fault lines, seismic activity is considered a separate peril that requires a standalone policy or endorsement purchased through your primary carrier or the California Earthquake Authority.
- What is the California FAIR Plan and who qualifies? The FAIR Plan is a state-mandated residual market mechanism that provides basic property insurance to homeowners who have been denied coverage by at least two voluntary insurers. It primarily serves residents in high-risk wildfire or coastal erosion zones who struggle to find voluntary market options.
- How can I lower my California home insurance premiums? You can lower your premiums by installing fire-resistant roofing, maintaining a defensible space around your home, bundling your home and auto policies with the same carrier, increasing your deductible, and installing smart home safety devices like leak detectors and fire alarms.
- Does California homeowners insurance cover wildfire smoke damage? Yes, standard policies generally cover smoke damage caused by wildfires as part of the fire peril, though you must document the damage thoroughly and prove it was not caused by a general negligence issue unrelated to the wildfire event.
- What is the difference between actual cash value and replacement cost in dwelling coverage? Actual cash value pays to replace your home minus depreciation, while replacement cost coverage pays the full amount required to rebuild your home to current building codes without deducting for depreciation. In California, replacement cost is highly recommended due to the high cost of labor and materials.
Conclusion
Navigating the complexities of California homeowners insurance demands vigilance, education, and a proactive mindset. With the ever-present threats of wildfires, earthquakes, and severe weather, relying on a generic policy is a gamble that no homeowner should take. By understanding the unique challenges of the Golden State, leveraging specialized programs like the FAIR Plan, and continuously optimizing your dwelling coverage California residents need, you can achieve peace of mind. Protect your sanctuary today, so that no matter what nature throws your way tomorrow, your home remains a safe and resilient haven for years to come.